Cyprus and Liechtenstein have finalized a double taxation agreement to eliminate double taxation of income and prevent tax evasion. The Cyprus Ministry of Finance announced this on November 12, 2026.
The ministry described the agreement as an important step toward strengthening economic relations between the two countries. The agreement is expected to increase tax certainty and create more favorable conditions for international business and investment.
Why Does Cyprus Need an Agreement with Liechtenstein?
The main purpose of the agreement is to prevent a situation where the same income is taxed simultaneously in both countries. This is particularly important for companies and individuals who conduct business, invest, or earn income in both Cyprus and Liechtenstein.
The agreement is intended to provide clearer rules for the taxation of cross-border transactions, reduce the risk of tax disputes, and simplify cooperation between the tax authorities of the two countries.
According to the Liechtenstein tax administration, the agreed-upon document provides for a zero withholding tax rate on dividends, interest, and royalties. It also regulates the taxation of certain asset management structures, investment funds, and pension funds.
What Will Change for Businesses and Investors
The new rules may benefit several categories of taxpayers:
companies operating simultaneously in Cyprus and Liechtenstein;
entrepreneurs engaged in international business;
investors receiving dividends and other investment income;
individuals with sources of income in both countries;
investment and pension funds.
In addition, the agreement provides for the exchange of tax information between the two countries and a mechanism for resolving disputes. The document was drafted in accordance with international standards and the requirements of the OECD/G20 BEPS project, which aims to combat tax evasion and the artificial shifting of profits.
When the agreement will take effect
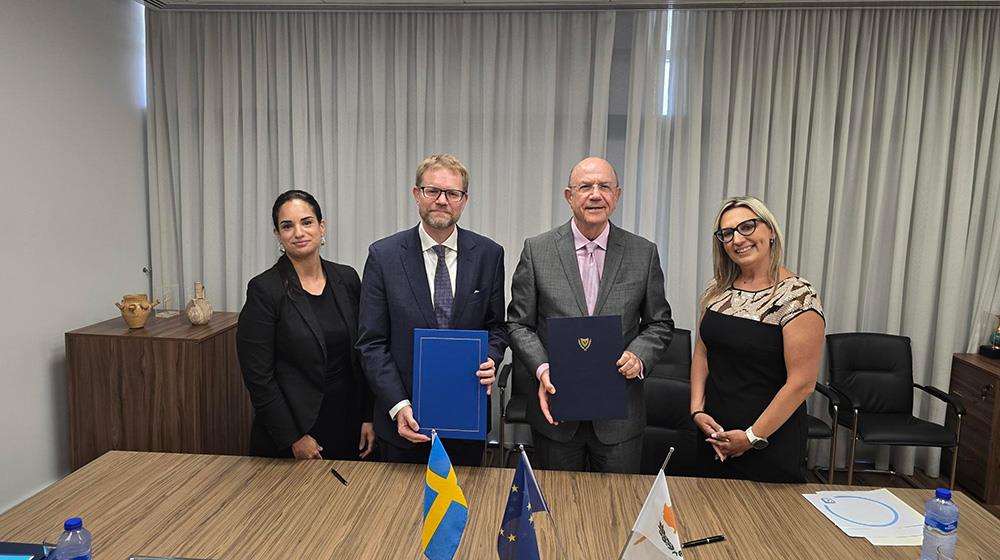
Despite the announced conclusion of negotiations, the new tax rules have not yet entered into force. On November 12, 2026, the tax authorities of both countries initialed the agreement. This means that the parties have agreed on the final text of the document. The next step will be its official signing and the necessary ratification procedures.
The text of the agreement is scheduled to be published after it is signed. The date the agreement will take effect has not yet been announced.